What Happens If A Title Loan Company Repossesses My Vehicle?
The laws covering repossession in the State of Texas are straightforward. Once you default on a title loan contract in Texas, a lender can legally repossess your vehicle without prior notice. That means you could face repossession not long after missing your monthly payment. While Texas law allows "self-help" repossession without a court order, reputable lenders often offer a grace period or a notice of default as a best practice.
Now that we've covered the heavy stuff, let's discuss what usually happens when you fall behind on title loan payments and what you can do to avoid it. Keep in mind that having your vehicle repossessed is scary, but it's not the end of the world. Consumer protections are in place to help you recover your vehicle, and companies offering Texas title loans must comply with the law at every step of the repossession process.
Why Would A Lender Not Want To Repossess Your Car?
In most situations, your lender will want to avoid repossessing your vehicle and will work with you to get back on track with the payments. Repossession costs money, and they would rather avoid the expense of hiring a tow truck driver and storing your vehicle before it's sold at auction.
Excess costs increase their losses when they initiate the repo process, and it's in their best interest to get you back on track with payments. Besides that, they make their money off the interest and fees you pay each month. Talk to any reputable lender, and most will confirm they'd rather you make on-time monthly payments than deal with the expenses and hassle of a repossession.
In many Texas cities, local ordinances require each payment or renewal to reduce your principal by at least 25%. These regulations can help prevent a repossession by ensuring you actually pay down your principal.
Protect Yourself From A Repossession in Texas
It is important to work with a company licensed by the Office of Consumer Credit Commissioner (OCCC). These companies are closely monitored for compliance and must strictly adhere to the Texas Finance Code. You can verify any lender's license using the OCCC's online license search. The best bet is to work with fully licensed lenders and ask each one about their process if you fall behind on payments.
Most larger title loan companies in Texas have both positive and negative reviews online, which is understandable. However, lenders that aggressively repossess vehicles will likely have far more complaints from customers who feel they were unfairly targeted or not given due notice of a repossession.
How To Avoid A Title Loan Repossession
The first step is to familiarize yourself with the current title loan repossession laws and use that information to avoid losing your vehicle. This is easier said than done because the rules can change. Most companies will offer you a title loan according to the information you provide on a credit application. Do what you can to repay the loan quickly.
If possible, pay off the loan in full. If not, contact customer service to see if you can renegotiate the payment terms. Consider refinancing or a buyout of the existing loan to get a fresh start and new financing terms.
Contact your loan representative immediately if you think you may fall behind on payments. Most local title lenders will want to work with you to keep payments current, and they will likely try to set up a payment plan or reduce the amount owed for specific months if you're facing financial hardship.
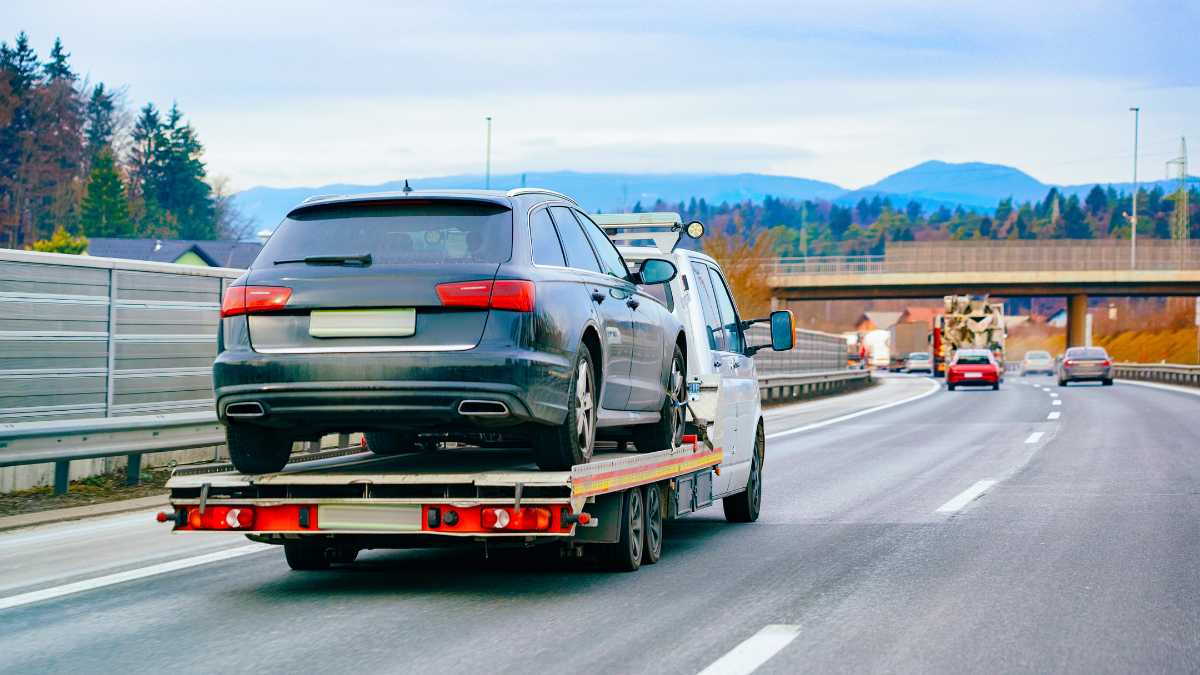
Understanding how and where a repossession can legally take place in Texas is the best way to protect yourself. Under Texas repossession laws, your lender can recover your vehicle on public property or an accessible driveway, but they cannot breach the peace or enter a locked garage without your permission. Don't try to hide the vehicle or move it to another state. Instead, use the remaining time the car is in your possession to negotiate with your lender. Two options to consider in this situation are a loan deferment or, if possible, a buyout.
Your Options If You're Facing Repossession
Just because your lender threatens to repossess your vehicle doesn't mean you're out of options. While the clock is ticking, we can help you if you're in danger of losing your vehicle.
We work with multiple Texas lenders who can refinance your existing loan. That means you may be able to secure a lower monthly payment, and you may receive a lower interest rate if you qualify for a refinance. Another option is to have your original loan bought out and start fresh with terms and payoff amounts that work for your budget. We often speak with customers who are just weeks away from vehicle repossession, and we can sometimes get them pre-approved for a buyout or, at the very least, explain their consumer rights under their city's ordinance. Keep in mind that if you're in a Texas city with a local ordinance, a new lender can only buy out your loan if the remaining balance is within the ordinance cap (the lesser of 70% of the car's retail value or 3% of your gross annual income).
A loan buyout and some other alternatives to a repossession must be finalized before a repossession agent takes the vehicle. Once a lender has possession of your vehicle, there's not much you can do other than pay the balance owed plus repossession fees to get the car back before it's sold.
If you can't pay off your loan and your car gets repossessed, your lender will typically sell it at auction. They must notify you before the sale, and whatever your car sells for will go toward the balance. If your vehicle sells for less than you owe, you may still be responsible for the difference, which is called a deficiency balance. On the other hand, if the car sells for more than what's owed, the extra money will be sent back to you.
Call us at 844-243-3195 to learn how we can help you avoid an imminent repossession. We'll put together a new payoff estimate using just your current loan information and desired repayment terms, and you'll usually receive an estimate within 30 minutes. There's no risk in calling us to explore your options, whether that means negotiating with your current lender or finding a new one.